 Follow on Google
When starting or expanding a business, it’s typical for lenders to request security in the form of property or other assets. And this is precisely what many small business owners find hard to arrange when applying for business finance.
If you don’t have substantial savings or expensive machinery or property to offer as collateral security, securing a business loan can be a major challenge – especially if you’re a first-time entrepreneur.
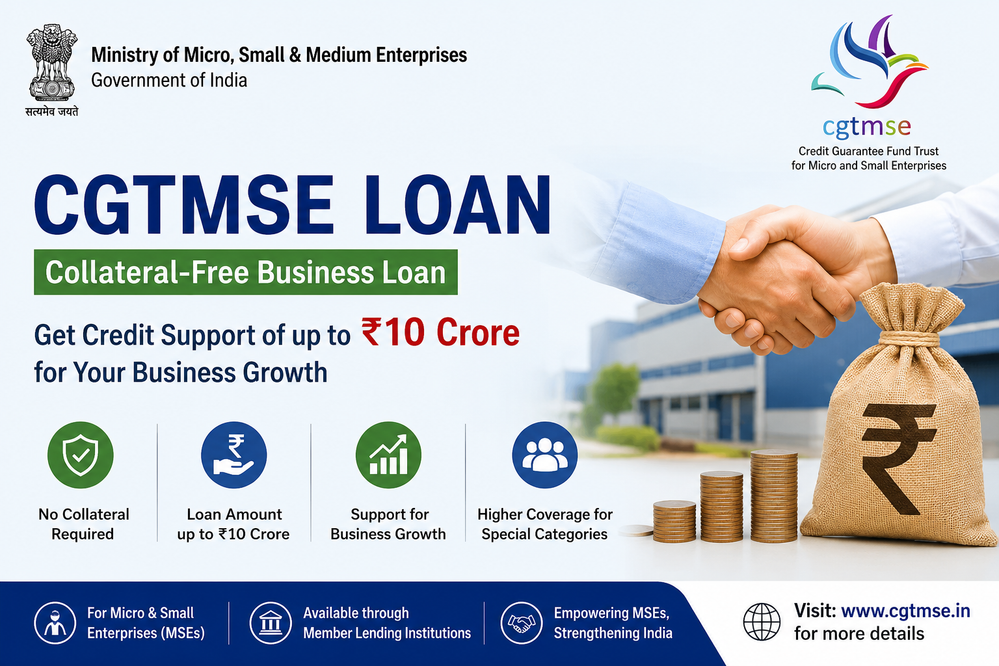
That’s where CGTMSE comes in. Launched by the Government of India, Credit Guarantee Fund Trust for Micro and Small Enterprises or CGTMSE helps eligible micro and small businesses avail finance for their business without collateral security or third-party guarantee.
What Is a CGTMSE Loan?
CGTMSE stands for Credit Guarantee Fund Trust for Micro and Small Enterprises.
A CGTMSE loan can refer to a business loan approved by a CGTMSE member lending institution as part of the Credit Guarantee Scheme.
Eligible lenders can provide credit under the scheme including term loans and working capital facilities without collateral security to eligible Micro and Small Enterprises. The guarantee coverage extended by CGTMSE aims to mitigate the lender’s credit risk and allow viable businesses to access formal credit.
CGTMSE has increased the maximum guarantee cover amount for eligible credit facilities up to ₹10 crore for eligible banks and financial institutions.
Note that the maximum guarantee cover may vary based on the category of lending institutions.
Key Benefits of CGTMSE Loan
Here are some important reasons why CGTMSE loans can be beneficial for small business owners.
1. No collateral required
CGTMSE loans offer the benefit of obtaining credit without the need for traditional collateral security or third-party guarantee for scheme-covered facilities.
2. Funds to support your business
If you’re approved for credit under CGTMSE, you can use the funds to meet your business needs. This can include buying machinery, expanding your business, meeting working capital requirements, or enhancing your business’ production capacity.
3. Higher guarantee coverage for loans
The guarantee coverage under CGTMSE depends on the category of the borrower and the amount of credit. However, women entrepreneurs, entrepreneurs in the North East Region, SC/ST entrepreneurs, eligible enterprises in Aspirational Districts, and certain other categories can enjoy higher guarantee coverage under the scheme.
4. Eligible loans go up to ₹10 crore
Subject to lender eligibility and scheme rules, borrowers may avail of guarantee coverage on loans up to ₹10 crore from eligible lenders.
CGTMSE Loan Eligibility
When it comes to determining CGTMSE loan eligibility, there are a few key criteria that typically must be met.
The applicant must:
- Have or set up a Micro or Small Enterprise (as per eligibility).
- Apply to a bank, financial institution or other eligible Member Lending Institution (MLI) that is registered with CGTMSE.
- Apply for an eligible business loan or credit facility.
- Meet the lending institution’s set criteria for credit appraisal and viability.
- Meet the requirements of CGTMSE’s scheme.
Remember that just because CGTMSE loans are offered without collateral security doesn’t mean the business loan will be approved without due diligence. Lending institutions will still thoroughly assess your business proposal, repayment capacity, financials, and overall business viability. Don’t confuse collateral-free loans with hassle-free loans.
How to Apply for a CGTMSE Loan
The easiest way to apply for a CGTMSE loan is through a lending institution.
Step 1: Find a Member Lending Institution
Search for a bank, financial institution or other lender who is a CGTMSE Member Lending Institution. Submit your business loan application to the lender of your choice.
Step 2: Apply for Your Loan
Submit all required documents to your lender. This will likely include your business registration documents, PAN card, Aadhaar card, bank statements, business plan, financial information, among others.
Step 3: Wait for the lender to credit assess your loan application.
The lender will review your loan application as per their lending policies and criteria.
Step 4: Apply for CGTMSE Guarantee
If your loan is approved by the lender and is eligible, the lending institution will apply to CGTMSE for guarantee coverage. The lender will not require you to apply directly to CGTMSE.
Note: While there may be agents or websites claiming they can help you get a CGTMSE loan approved, it’s best to deal with your lender directly. Please note that CGTMSE has warned entrepreneurs about several websites and agents that have been posing as CGTMSE representatives.
Keep these things in mind before you apply
It helps to compare loan offers from multiple lenders to see which terms are suited to your business needs.
Business owners should be prepared with a detailed business plan when they apply. This includes a strong repayment plan and realistic financial projections. Remember that the quality of your loan application is just as important as finding collateral-free loans.
Final Word
CGTMSE can help qualified small business owners access the funds they need to grow their business even if they don’t have collateral or property to offer as security. The Credit Guarantee scheme allows eligible lenders to give credit without collaterals to MSEs by providing them with guarantee coverage.
If you think your business loan qualifies under CGTMSE guidelines, approach a member lending institution to apply. Check with your lender if your loan can be backed by CGTMSE and meets the eligibility requirements under the scheme.
With loan guarantees up to ₹10 crore for eligible lending categories, CGTMSE continues to enable greater access to credit for India’s micro and small businesses.
Visit CGTMSE Official Website for more information on scheme rules and eligibility.
Follow on Google