 Follow on Google
The Kisan Vikas Patra (KVP) Scheme is a small savings scheme targeted at investors who want capital protection with fixed long-term returns. But that doesn’t mean that farmers can’t invest in it. Under this scheme, any eligible Indian resident can invest in KVP at specified Post Offices and authorised banks.
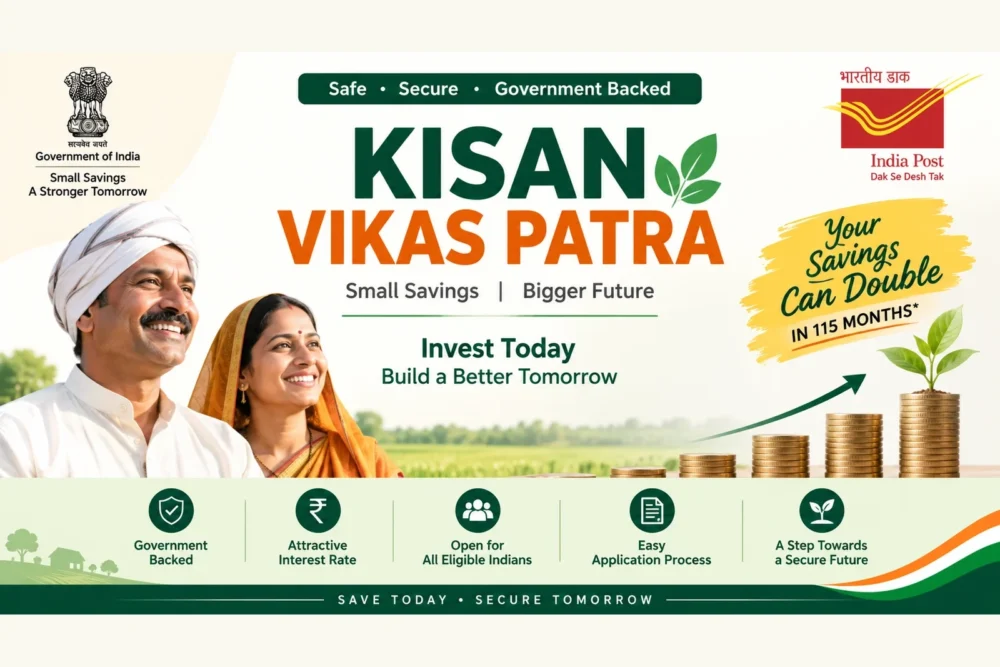
And its biggest benefit is extremely simple to understand. At the applicable rate of interest, your invested capital will DOUBLE in a fixed period of time.
What Is the Kisan Vikas Patra Scheme?
Kisan Vikas Patra, or KVP, is a government-backed small savings scheme that Indian residents can invest in. If you prefer products that aren’t market-linked and want your capital protected with fixed returns then KVP could be right for you.
KVP has an interest rate of 7.5% per annum compounded annually for the July–September 2026 quarter. Under the applicable rates, your invested capital will mature in 115 months.
That means if you invest ₹1 lakh in KVP, you can expect around ₹2 lakh back at maturity.
Kisan Vikas Patra Interest Rate 2026
The current KVP interest rate is:
- Interest Rate: 7.5% per annum
- Compounding: Annually
- Maturity Period: 115 months
- Return: Investment amount doubles at the prescribed maturity
It’s important to note that the Government reviews small savings interest rates from time to time. So make sure to review the applicable interest rate before investing.
Who Is Eligible for Kisan Vikas Patra?
KVP accounts can be opened by eligible resident Indians. There are different categories under which KVP accounts can be opened, including:
- Individual accounts opened by an adult
- Joint account by a maximum of three adults
- Minor’s account opened by the guardian
- Minor’s own account if they are aged 10 years or more
So while KVP technically means farmer’s development certificate, any investor who qualifies under these criteria can open a KVP. That includes farmers, salaried individuals, families, etc.
Minimum and Maximum Investment
The minimum investment requirement for the Kisan Vikas Patra Scheme is pretty low:
- Minimum investment: ₹1,000
- Additional investments can generally be made in multiples of ₹100
- No maximum investment limit, subject to applicable rules and documentation requirements
There’s no restriction on owning more than one KVP certificate, as long as you adhere to the prevailing regulations and limits. Additional documentation may be required for larger investments.
How to Apply for Kisan Vikas Patra
Opening a Kisan Vikas Patra account is a simple process. Simply visit your nearest Post Office or bank where KVP investments are accepted.
Opening Kisan Vikas Patra Account: Step-by-Step
Step 1: Visit the Post Office/ bank
Step 2: Ask for the KVP application form and fill it out.
Step 3: Submit your KYC documents.
Step 4: Provide your PAN and Aadhaar details. (or other officially accepted documents)
Step 5: Pay the amount for which you want to invest in KVP.
Step 6: Safely store the account and investment details for future reference.
Required documents to apply for KisanVikas Patra includes the account opening form, KYC documentation, PAN card and Aadhaar card or officially accepted documents for identification.
Key Benefits of Kisan Vikas Patra
1. KVP Is Government Guaranteed
As mentioned above, Kisan Vikas Patra is an Indian Government backed savings scheme. This benefit alone is attractive to many investors.
2. Stable Returns
If you invest in KVP your returns are market-independent. You’ll earn interest at the rate applicable to your investment as per the scheme guidelines.
3. There Is No Maximum Investment Limit
There is no upper limit on how much you can invest in KVP. However, you’re still subject to KYC and tax laws.
4. KVP Accounts Can Be Transferred
If you have multiple KVPs, you can transfer them as per rules of the scheme.
5. Premature Closure Allowed
KVP accounts can be closed before maturity, subject to certain conditions. Note that after 2 years and 6 months, you can apply for normal premature encashment. However, there are certain conditions that allow account holders to apply for premature closure on “exceptional grounds” such as death of the investor. It is best to consult the scheme rules for more information on premature closures.
Is Kisan Vikas Patra a Good Investment?
If you’re after a simple investment that protects your capital with guaranteed long-term returns then Kisan Vikas Patra can be a great investment choice. Just keep in mind that you’ll need to leave your money untouched for at least 8 years.
As with any investment decision, you should assess KVP against other available options based on your financial goals and needs.
Final Thoughts
The Kisan Vikas Patra Scheme 2026, true to its title, offers a clear and uncomplicated way for individuals to save money with government backing over an extended period. Offering an interest rate of 7.5% p.a. and the maturity period of 115 months calculated on your eligible investment amount under the prevailing rate KVP could be an attractive investment option for those investors who are ready to trade-off liquidity for certainty against volatility in market.
While applying for KVP, please note that rate of interest and rules pertaining to all small saving schemes are subject to change by Government and India Post from time to time, so please re-confirm the latest rules directly from Government and India Post approved sources before applying.
Follow on Google