 Follow on Google
How to Invest in Gold without Buying Physical Gold? That’s where sovereign gold bonds (SGB) comes in. Originally launched as an alternative to owning coins or gold jewellery, SGBs allow investors to buy bonds linked to gold prices, earn fixed interest and get the underlying gold value of the investment at maturity.
When considering SGBs in 2026, it’s crucial to remember that the Reserve Bank of India’s most recent Sovereign Gold Bond issuance was for the 2023-24 period. New subscription windows do open for fresh issues, but do NOT assume that you can apply to buy SGBs right now.
Here’s everything else you need to know about SGBs.
What is the Sovereign Gold Bond Scheme?
As the name suggests, the Sovereign Gold Bond Scheme issues government-backed gold bonds that are traded like other debt instruments. These are issued by the Reserve Bank of India (RBI) on behalf of the government.
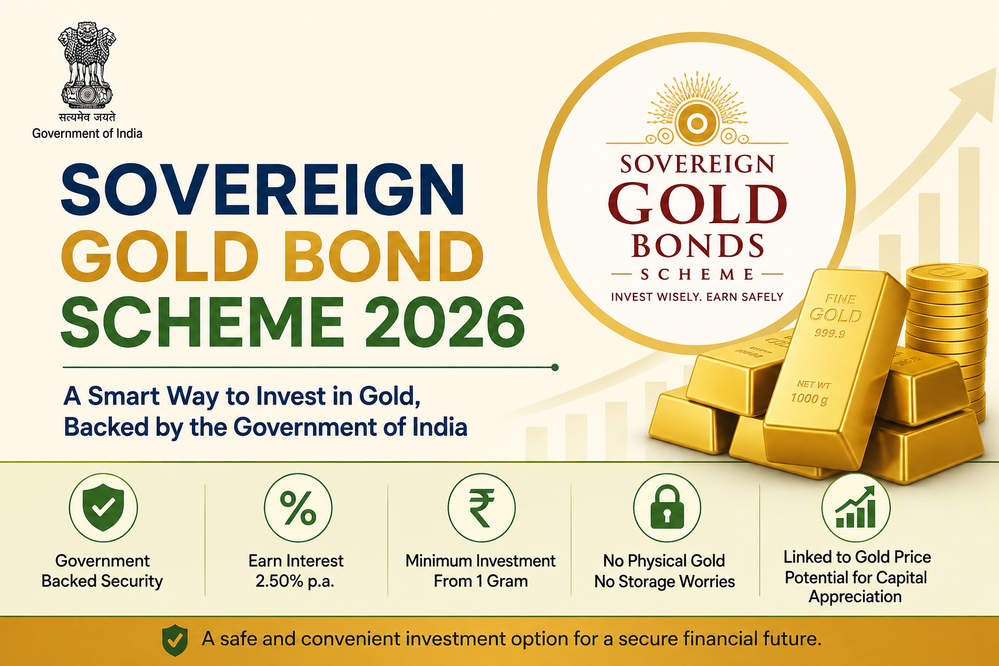
Instead of buying gold in physical form (such as coins or bars), investors can buy bonds equivalent to the market value of gold. SGBs are denominated in gram denominations, with each bond representing 1 gram of gold. The minimum investment is for 1 gram of gold.
Investors don’t need to worry about storing gold bullion at home or making charges like they would for gold jewellery.
Sovereign Gold Bonds have an 8-year maturity from the issue date. However, SGB investors can also redeem their bonds prematurely after the 5th year on specific interest-payment dates.
Who is Eligible for Sovereign Gold Bonds?
SGBs are available to:
- Resident individuals
- Hindu Undivided Families (HUFs)
- Trusts
- Universities
- Charitable institutions
For resident individuals and HUFs, subscription is limited to a maximum of 4 kg in a financial year. Rules for trusts and other eligible institutions allow for higher subscriptions of up to 20 kg in a financial year.
SGB investment by a minor is allowed in the minor’s name if made by a guardian.
Sovereign Gold Bond Interest Rate
The interest rate is one of the selling points of Sovereign Bonds. The RBI currently pays investors a fixed 2.50% per annum interest on their SGB investment.
Interest is calculated annually based on the nominal value of these bonds. It is paid out twice a year and is completely independent of changes in gold prices.
So, total returns come from:
Interest payments + appreciation/depreciation in gold value
That said, unlike the interest component, any returns from gold price changes are not guaranteed.
Sovereign Gold Bond Benefits
1. No hassles of storing physical gold
Investors gain exposure to gold prices without needing to keep gold coins or bars at home.
2. Earn fixed interest
In addition to the gold price value of your investment, you’ll also earn a fixed interest rate of 2.50% per annum.
3. Government-backed investment
Issued by the RBI on behalf of the Central Government, SGBs are backed by the full faith and credit of the government.
4. Bonds can be pledged as collateral
SGBs can be pledged as collateral for loans, subject to the lender’s terms and RBI regulations.
5. Making charges and purity
Finally, there are no concerns about making charges like you would when buying gold jewellery. Additionally, the gold quality is assured for SGBs whereas actual gold bars can vary in purity.
How to Apply for Sovereign Gold Bonds?
If and when the government announces a new Sovereign Gold Bond issue, subscribers can apply through participating banks, the Stock Holding Corporation of India Limited, specified post offices and recognised stock exchanges. The official issue notification will provide details on how to apply.
Customers will be required to fulfill KYC requirements and submit documents including their PAN.
Remember: Because the Indian government has not regularly issued new Sovereign Gold Bonds in recent years beyond the 2023-24 series, it’s important to double check whether new subscriptions are currently open on the RBI’s official SGB page. Don’t assume that you can buy SGBs based on application dates you may have seen from previous years.
Sovereign Gold Bond Tax Benefits in 2026
Interest earned on SGBs will be taxed as per the income-tax rules that apply to you. The government has also revised the tax rules for exempting capital-gains at maturity.
Effective April 1st, 2026, SGB capital-gains will only be exempt if the bonds are held from the original issue date by an individual until maturity.
To be clear, if you purchase SGBs from the secondary market, they won’t be eligible for this tax exemption unless you hold onto them until they mature, starting from your purchase date.
Is Sovereign Gold Bond Still Worth Considering?
Gold Bonds can be a great way to invest in gold over the long term without worrying about the inconvenience of physical gold. However, SGBs are not bank deposits, nor do they offer guaranteed returns. The market price of gold can go up or down.
If you’re looking to buy SGBs in 2026, make sure a new issue is currently available from the government. Don’t simply rely on old advertisements or “apply till” dates that you may have seen on the web from previous years.
Quick Facts
| Feature | Details |
|---|---|
| Issuer | RBI on behalf of Government of India |
| Minimum investment | 1 gram |
| Individual limit | 4 kg per financial year |
| Interest | 2.50% per annum |
| Interest payment | Half-yearly |
| Normal maturity | 8 years |
| Premature redemption | After 5 years, on specified dates |
| Linked asset | Gold price |
| KYC | Required |
Note: This article is for informational purposes only and is not meant to be taken as investment advice. Investors should always check the official government websites for the latest Sovereign Gold Bond issue notifications and tax rules.
Follow on Google